This explanation of rental income tax for property owners in Indonesia is for landlords, Bali property investors and owners deciding between an ordinary lease and an accommodation business. It separates the standard gross-rent tax from kost rules, nonresident questions and regional accommodation taxes, so you know which facts to confirm before filing.
How much is rental income tax for property owners in Indonesia?
The standard income tax on ordinary land and building rent is a final tax of 10% of gross rental income, not rental profit. It is commonly called PPh Final Pasal 4(2), or Article 4(2) final income tax, and is governed by PP 34/2017 on land and building rentals.
The regulation took effect on January 2, 2018. This is therefore not a newly introduced tax on landlords, even if an owner has only recently encountered it.
DJP, Indonesia’s Directorate General of Taxes, provides a useful modest-rent example: annual house rent of Rp24 million produces Rp2.4 million in tax. That example concerns ordinary house rental, with the landlord paying because the individual tenant is not a withholding agent.
Before applying that calculation to your own property, establish:
- Whether the activity is ordinary property rental or accommodation services.
- Whether the recipient is resident or nonresident for Indonesian tax purposes.
- Which associated charges belong in gross rental value.
The standard rate is a starting point, not a universal answer for every villa, boarding house or overseas owner.
What charges count as gross rental income in Indonesia?
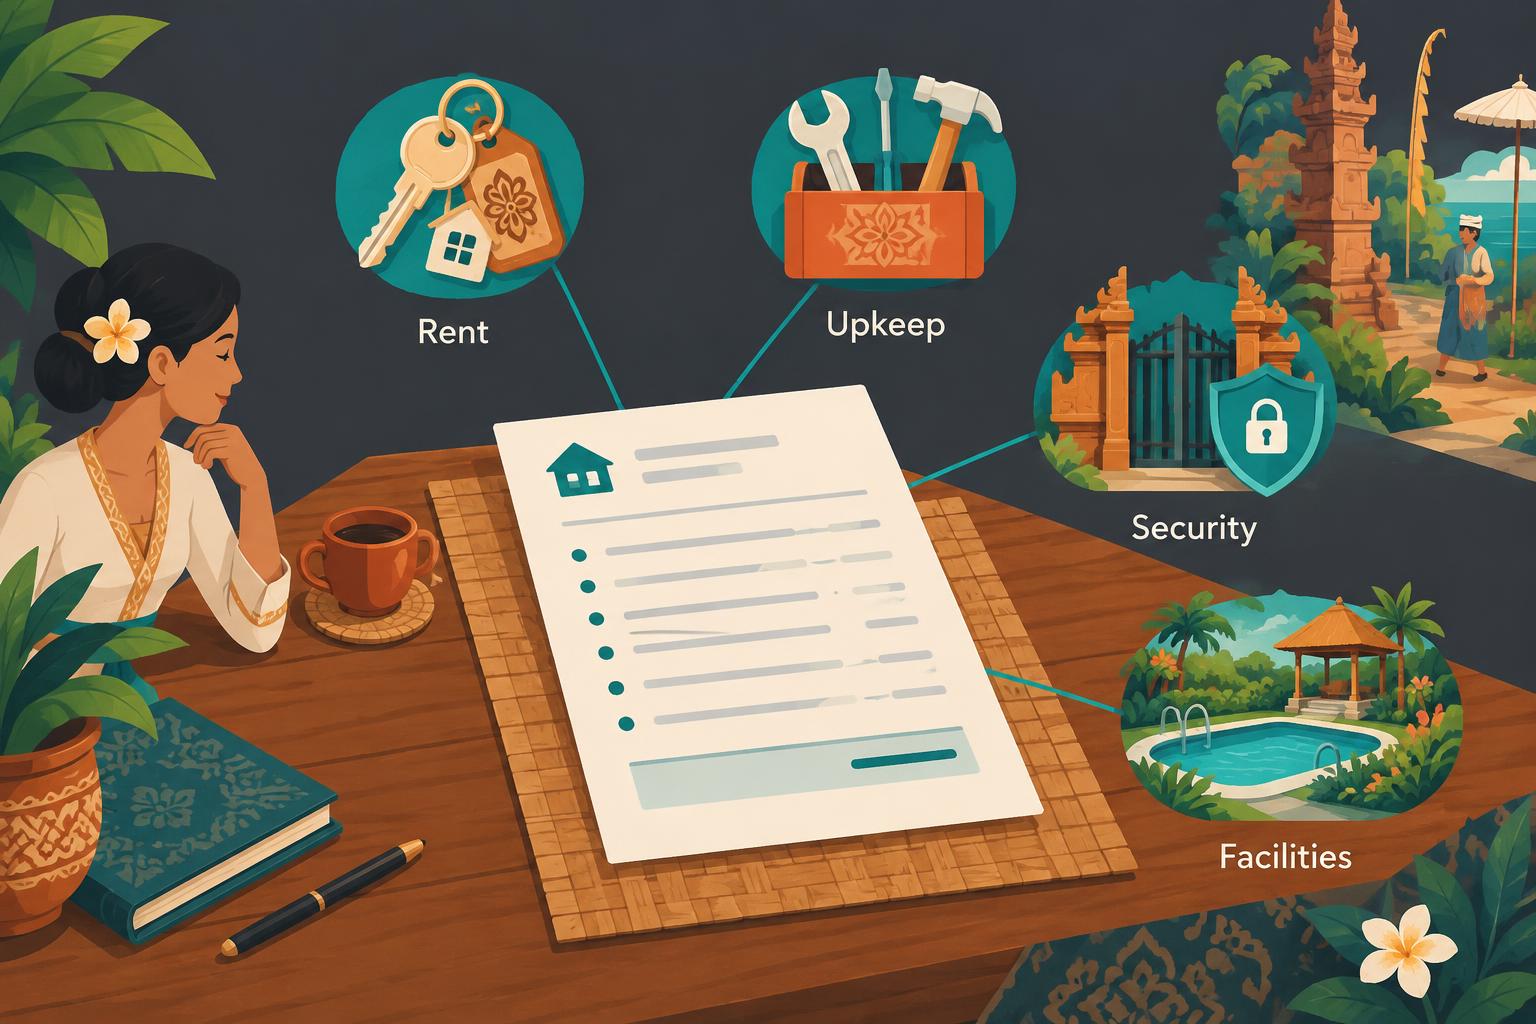
Gross rental income includes rent and associated maintenance, upkeep, security, service and other facility charges covered by the ordinary rental rules. PP 34/2017 includes these charges even when they appear in separate agreements.
For a Bali property owner, the practical risk is treating the headline rent as the entire tax base while placing property-related charges elsewhere. A separate maintenance invoice does not, by itself, remove that amount from gross rental value.
Build a reconciliation from the lease and supporting invoices:
- Identify the base rent.
- List maintenance, security and facility charges associated with the rental.
- Check who receives each payment and what it actually pays for.
- Ask your adviser about ambiguous items rather than assuming that a separate invoice makes them exempt.
The distinction matters when rent includes pool care, shared facilities or other ongoing services. Our explanation of Bali utility costs and rental inclusions can help you identify the household expenses to document, but an expense label alone does not determine its tax treatment.
Keep the commercial breakdown clear for the tenant while calculating the tax base under the regulation, rather than simply copying whichever line is labelled “rent.”
Can landlords deduct repairs, mortgage costs or management fees?
Expenses do not reduce the gross-rent base used to calculate the standard 10% final rental income tax. Repairs, financing costs and management expenses may reduce the money an owner retains, but this tax is calculated on gross rental value rather than profit after those costs.
Keep two separate calculations in your property accounts:
- Tax calculation: the applicable final tax on gross rental value.
- Investment calculation: rental receipts less operating costs, financing costs, tax and other outgoings.
Confusing those calculations can make an investment look more profitable than it is. A substantial repair bill does not automatically produce a corresponding reduction in ordinary final rental tax.
Livuma’s property hosting guide explains its host platform fee on successful paid bookings. Keep that fee identifiable in your accounts rather than treating the net payout as automatically equivalent to taxable gross rent.
The same discipline applies when a property manager collects money and sends you a balance after deductions. Ask for a statement showing the underlying rental receipts and each deduction, not only the amount transferred to your bank account. Accommodation businesses may fall under a different income-tax framework, so establish the category before using this gross-rent calculation.
Does the tenant withhold rental tax, or does the landlord pay it?
A designated withholding-agent tenant withholds the applicable final rental tax; otherwise, the landlord pays it themselves. The tenant’s tax status therefore affects the payment process, even where the underlying ordinary rental-tax calculation is unchanged.
Under PP 34/2017, withholding tenants include government bodies, Indonesian corporate taxpayers, permanent establishments and other designated tenants. A private individual renting a home usually is not a withholding agent.
Before collecting rent, confirm:
- The legal identity of the tenant, rather than only the person occupying the property.
- Whether that tenant acts as a designated withholding agent.
- Whether the quoted amount and expected bank transfer reflect the agreed withholding treatment.
- Who will provide the supporting tax documentation.
DJP’s explanation of house-rental tax confirms that the landlord pays where the individual tenant is not a withholding agent.
Do not assume that appointing an agent or collecting rent through a marketplace settles this question. Identify the responsible taxpayer and withholding party explicitly, then reconcile the gross rental amount, any tax withheld and the cash actually received.
When must Indonesian rental tax be paid and reported?
Article 4(2) income tax is generally payable by the 15th of the following month, with monthly reporting generally due within 20 days after the tax month ends. These are separate obligations, and statutory exceptions need checking for the particular taxpayer.
Effective January 1, 2025, PMK 81/2024 on core tax administration changed the general payment deadline. Older instructions referring to a withholding-payment deadline on the 10th should not be used without checking them against the applicable rules.
Article 171 generally provides for Article 4(2) reporting through the unified monthly income-tax return. Ask your accountant to confirm the relevant tax month, particularly where a lease involves advance payments or a payment schedule that differs from the occupancy period.
Final tax does not mean unreported income. DJP also instructs landlords to disclose ordinary rental income in the final-tax-income section of their annual income-tax return.
Your compliance calendar should therefore distinguish:
- Payment of the tax.
- The applicable monthly reporting requirement.
- Disclosure in the annual return.
Keep payment evidence and withholding documents with the corresponding rental records so the monthly and annual figures can be reconciled.
Is rental income tax for property owners in Indonesia different for foreigners?
Nationality alone does not determine an owner’s rental-tax treatment; tax residence and the applicable nonresident rules require separate assessment. Neither “foreigners always pay 20%” nor “every landlord pays 10%” is a safe universal statement.
DJP’s published individual residence criteria include residence in Indonesia, presence exceeding 183 days in any 12-month period, or presence during a tax year with an intention to reside. A passport is therefore not enough to classify the recipient.
For a nonresident recipient, do not assume that the ordinary 10% rental-tax treatment applies automatically. The applicable withholding rules and any relevant tax treaty require case-specific confirmation.
For an overseas owner, obtain case-specific confirmation covering:
- The income recipient’s tax residence and legal identity.
- The nature of the Indonesian rental activity.
- Any relevant treaty and supporting documentation.
- The applicable withholding article and payment process.
Our explanation of Indonesian tax residency for expats provides background on residence questions. It does not determine your nonresident rental-tax treatment or replace advice on your own facts.
Are Bali villas and kost taxed like ordinary house rentals?
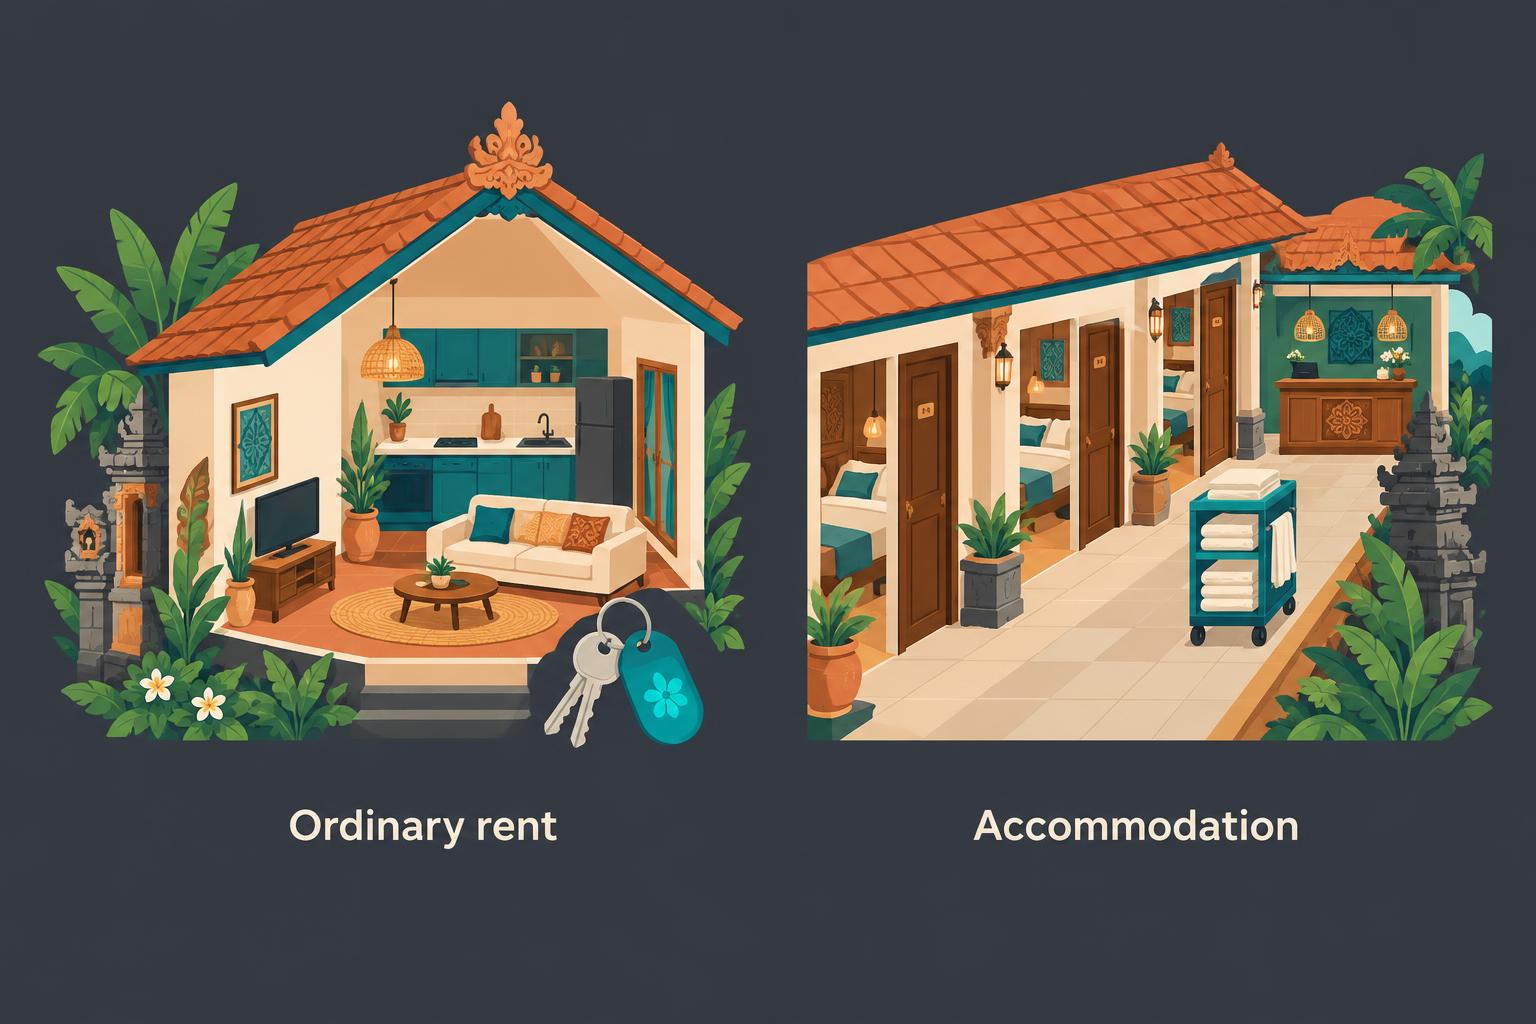
Not necessarily: PP 34/2017 expressly excludes accommodation services from the ordinary 10% final rental regime. Its explanation includes rooms, student or worker accommodation, and kost or boarding houses within the accommodation category.
The difficult question is what the operation actually provides. DJP’s August 11, 2026 explanation says that the property’s label, monthly versus annual payment, and furnished status are not individually decisive in distinguishing ordinary rental from accommodation activity.
That means you should not classify a property solely because:
- The listing calls it a “villa,” “house” or “kost.”
- The guest pays monthly rather than annually.
- The premises include furniture.
- The owner operates only a small number of rooms.
DJP specifically states that the ten rooms or units used in its examples are not a national threshold determining central-government income-tax treatment.
Prepare a factual description of what the customer receives and how the business operates, then ask your adviser to classify that activity. Our Bali kost guide explains the renter-facing property type, but a marketplace category is not a tax ruling.
The practical distinction is between a lease and accommodation services—not simply between a cheap room and an expensive villa.
Can kost owners use the 0.5% tax rate or Rp500 million exemption?
Eligible individual kost operators may qualify for the 0.5% final small-business regime, but ordinary rental income does not gain the same treatment merely because the owner’s turnover is low. Classification comes before testing the relief.
DJP’s guidance identifies the small-business option where the taxpayer satisfies the rules and relevant aggregate annual turnover does not exceed Rp4.8 billion. Eligible individuals using that regime do not pay that income tax on their first Rp500 million of annual business turnover.
| Income category | Relevant treatment | Main qualification |
|---|---|---|
| Ordinary land or building rent | 10% of gross rental value | Standard rental regime; nonresident treatment needs checking |
| Eligible individual accommodation business | 0.5% final business tax | Eligibility rules and aggregate turnover limit of Rp4.8 billion |
| Eligible individual under that business regime | First Rp500 million of annual business turnover not taxed under the regime | Not an ordinary-rent exemption |
The DJP explanation of rental and kost taxation confirms that ordinary rent already subject to final tax under PP 34/2017 does not qualify for the small-business relief. Consequently, the Rp500 million provision should not be presented as a tax-free allowance for ordinary property rent.
Ask your adviser to test eligibility using the taxpayer’s relevant aggregate business turnover, not simply the revenue from a single property. A modest rental amount does not, on its own, change the applicable tax category.
Can a property company use the same small-business tax relief?
A property company cannot assume it qualifies for the 0.5% regime simply because an eligible individual accommodation operator might qualify. Entity type, registration circumstances and transitional provisions matter.
The changes introduced by PP 20/2026 on April 22, 2026 removed the previous time limit for qualifying individuals and qualifying single-person companies. They did not make the regime universally available to every business with modest turnover.
According to DJP’s explanation of the 2026 small-business changes, ordinary PT companies, CVs and firms newly registered from April 22, 2026 no longer qualify. Transitional provisions allow previously registered qualifying entities to continue until their existing eligibility period expires.
Before forecasting an accommodation investment through a company, establish:
- The exact legal form of the income recipient.
- Whether the income is ordinary rent or business income.
- Whether the entity has existing transitional eligibility.
- Which rules apply after any remaining eligibility ends.
Do not use an individual owner’s tax illustration as the company’s projected tax bill. Equally, do not assume that incorporating changes ordinary rental receipts into eligible small-business turnover. The income category and the recipient’s eligibility are separate questions that both need an answer.
Is rental income tax the same as VAT or Bali accommodation tax?
No: national income tax, VAT and regional accommodation taxes are different tax questions. A statement about one does not establish the treatment of the others.
DJP’s February 7, 2025 explanation confirms that qualifying hotel accommodation services—including villas and private residences operated as hotels—fall outside VAT under PMK 70/2022. That does not mean those operations have no income-tax or regional-tax obligations.
For a Bali accommodation business, separate the review into:
- National income tax: the income category and taxpayer’s applicable regime.
- VAT: whether the particular service falls within the qualifying hotel-accommodation treatment.
- Regional tax: the applicable PBJT hotel-services rules in the property’s jurisdiction.
Do not confuse the national 10% ordinary rental income tax with a regional accommodation levy just because a quoted percentage looks familiar. For Badung, the hotel-services PBJT rate under Perda 7/2023 remains 10%; Perda 8/2025, effective January 1, 2026, did not amend Article 28’s rate. Confirm the property-specific scope separately.
The useful question for an adviser is not simply “What is Bali’s villa tax?” It is which income, service, taxpayer and local jurisdiction are involved, and which separate obligations follow from those facts.
What rental records should an Indonesian property owner keep?
Keep records that connect the agreement, gross rental charges, deductions, tax evidence and actual money received. A bank statement alone may show a net receipt without explaining the underlying rental value or who accounted for the tax.
A practical property file should contain:
- The signed agreement and agreed payment schedule.
- A breakdown of rent and associated property charges.
- The tenant’s legal identity and confirmed withholding status.
- Invoices, receipts and statements showing deductions.
- Relevant withholding certificates and tax-payment evidence.
- The monthly and annual reporting reconciliation.
For supported bookings, Livuma generates digital rental agreement details and receipts from the listing, booking terms and verified guest details, giving both sides records to retain. Host payouts are released automatically about 24 hours after successful check-in under the booking’s terms, never while a reported problem is open; neither those documents nor the payout timing establish the applicable tax period, calculate tax or confirm that tax has been paid.
Give your accountant the agreement and transaction records together, and have them confirm how each payment maps to the relevant tax obligations.
What other Indonesian rental-tax questions do owners ask?
These short answers address common points that can otherwise distort an owner’s tax planning.
Is the 10% house-rental income tax a new tax?
No. The standard final income tax on ordinary land and building rent comes from PP 34/2017, which took effect on January 2, 2018. DJP’s August 11, 2026 explanation explicitly describes house-rental tax as not new. That does not mean every accommodation business or nonresident owner should automatically apply the ordinary rental treatment.
Does having fewer than ten kost rooms make the income tax-free?
No national ten-room threshold determines central-government income-tax treatment in the cited DJP guidance. DJP says the ten rooms or units in its examples are illustrative, not a threshold. The actual activity and taxpayer’s eligibility matter. Any regional accommodation-tax question must be assessed separately rather than inferred from that central income-tax explanation.
Did the 2026 changes abolish the Rp500 million business exemption?
No. DJP confirmed on September 29, 2026 that the provision remained in force after PP 20/2026 for eligible individuals using the final small-business regime. It concerns their first Rp500 million of annual business turnover. It is not an exemption for ordinary property-rental income already subject to the separate final rental-tax regulation.